
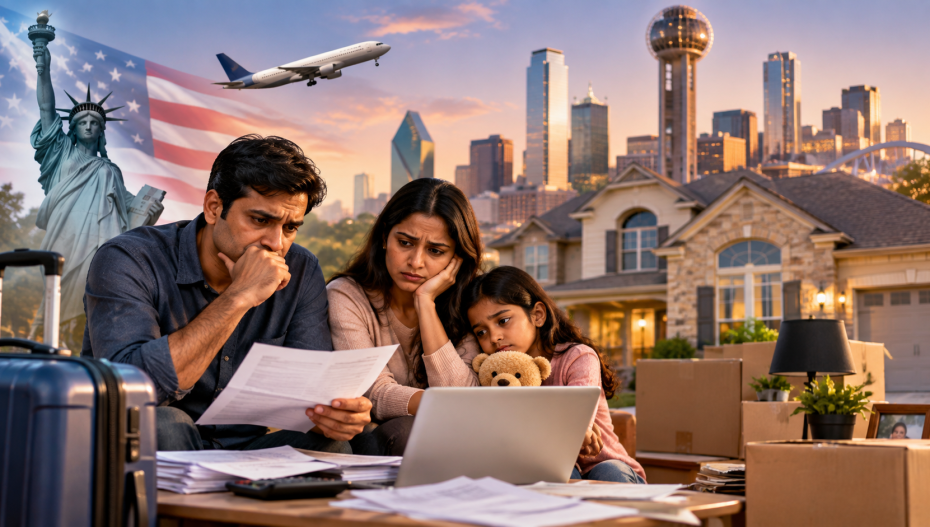
For some Indian families in the US, the question of whether to return to India is no longer only about a job.
There is also a house to pay for.
Families who bought homes during their years of employment in the US are now facing a difficult choice as job losses and uncertainty around H-1B-linked employment put pressure on their finances. Even if they decide to move back to India, their US mortgages and other financial commitments do not simply disappear.
The problem is particularly visible in Dallas-Fort Worth (DFW), Texas, which has a large Indian IT professional community and a strong presence of Indian buyers in the local housing market.
A local builder cited in the story said South Asian buyers, mainly Indians, once accounted for as much as 70% of luxury home sales in the area. Their share has now fallen to below 30%.
The sharp drop reflects a change in how some Indian families are approaching the US housing market.
Homes bought during the Covid period now bring a different pressure
During the Covid period, some Indian professionals bought homes when property prices were lower, according to the story. Many took on large mortgages while they had stable employment in the US.
But job losses and uncertainty over employment have changed that calculation.
A mortgage payment remains due even when a person’s job does not.
For families already thinking about returning to India, this creates another problem. Selling a US property is not necessarily an immediate solution. A home can take months to sell, leaving the owner responsible for mortgage payments and other property-related expenses during that period.
There is also the possibility of selling the property for less than expected.
If the home’s value falls below the outstanding mortgage, the owner could be left with a gap between the amount received from the sale and the amount still owed to the lender.
Returning to India does not mean leaving the financial obligations behind
For an Indian family dealing with employment uncertainty, moving back home may appear to offer a way out of the situation.
But a US property can make that decision more complicated.
A family may be back in India while still carrying a US home loan, an unsold property and other financial commitments. This can make the timing of a return particularly difficult for homeowners who do not have enough financial room to keep paying the mortgage for an extended period.
The issue therefore goes beyond immigration status. It reaches into decisions about property, debt and family finances.
The concern extends beyond H-1B workers
The uncertainty is not limited to H-1B visa holders.
Workers on other employer-linked visas, including L-1 visas, can also face employment-related uncertainty. If employment ends, families dependent on that income can suddenly find themselves dealing with commitments that were taken on when their US jobs appeared more secure.
The story also points to a proposed change from the US Department of Homeland Security (DHS) involving the current 60-day discretionary grace period for eligible H-1B and L-1 workers after employment ends.
If the proposed change takes effect, affected workers could face greater pressure when dealing with a sudden job loss and the decisions that follow.
A housing decision has become an employment decision
The shift in the Dallas-Fort Worth housing market shows how immigration and employment uncertainty can spill into other parts of family life.
For Indian IT professionals, buying a US home was often part of building a longer-term life in the country. But when employment becomes uncertain, the same property can become a major financial responsibility.
The fall in the reported share of South Asian buyers in luxury home sales — from as high as 70% to below 30% — points to a market where some Indian buyers are now becoming more cautious.
For families already owning homes, however, caution is no longer the only issue. They have to decide how to manage a mortgage, whether to sell, and whether they can return to India without leaving a large financial burden behind.
Also Read: 0.4% UPI Charge Sparks Trader Protest, October 2 Declared ‘No UPI Day’